Last updated: 15 October 2026 · By Analyst, Platizio Global
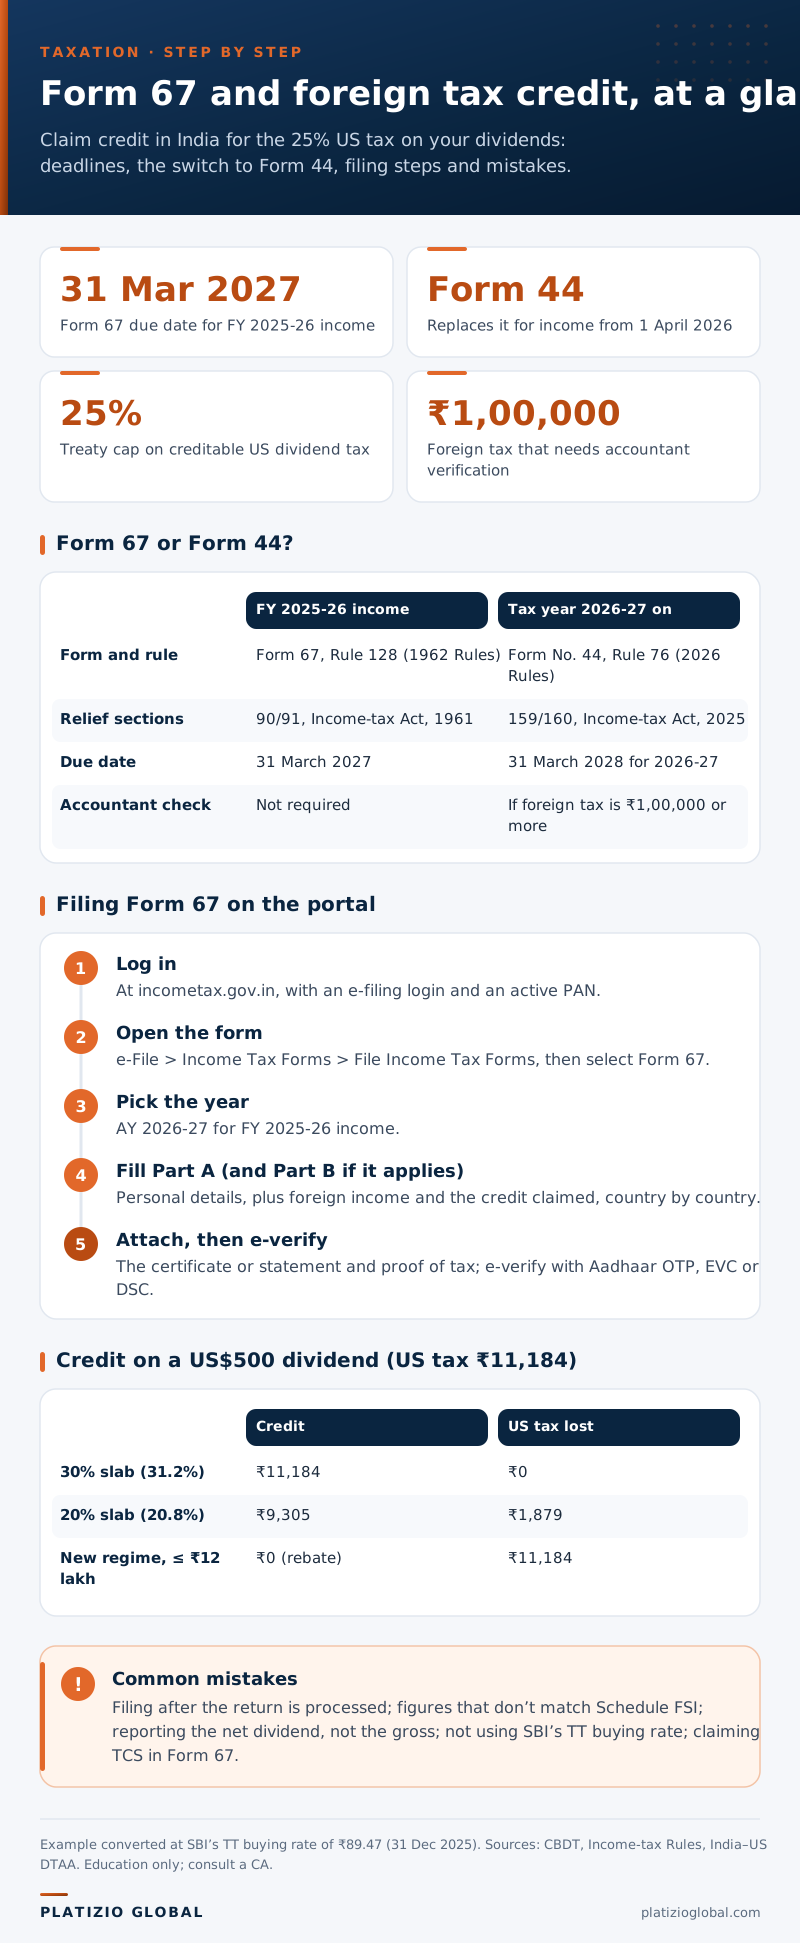
Form 67 is the statement you file on the income tax portal to claim credit for foreign tax, such as the 25% US tax on dividends. For financial year (FY) 2025-26 income, file it by 31 March 2027 if your return is filed on time or as a belated return. For income from 1 April 2026, use Form No. 44.
Key takeaways
- Due date: 31 March 2027 for FY 2025-26 income, provided your income tax return (ITR) is filed on time or as a belated return.
- From 1 April 2026: income is claimed in Form No. 44, due by 31 March 2028 for tax year 2026-27; an accountant must verify it if foreign tax for the year is ₹1,00,000 or more.
- Number reused: under the Income-tax Rules, 2026, “Form No. 67” is the alternate minimum tax report.
- Credit: the lower of the US tax withheld, up to the 25% treaty rate, and the Indian tax on the dividend.
What Form 67 is and who needs to file it
Form 67 is how you claim a foreign tax credit (FTC): a deduction from your Indian tax for tax already paid abroad on the same income. Rule 128 of the Income-tax Rules, 1962 allows the credit only if you furnish Form 67. For US income, relief comes under section 90 of the Income-tax Act, 1961.
File it if you are resident in India and foreign tax was withheld on income you report here, such as US tax on dividends from shares and exchange-traded funds (ETFs).
Form 67 due date, and when Form 44 applies instead
The Income-tax Act, 2025 replaced the 1961 Act on 1 April 2026 and uses “tax year” in place of “previous year” and “assessment year” (AY).
| FY 2025-26 income (AY 2026-27) | Tax year 2026-27 onwards | |
|---|---|---|
| Form and rule | Form 67, Rule 128 (1962 Rules) | Form No. 44, Rule 76 (2026 Rules) |
| Relief sections | 90/91, Income-tax Act, 1961 | 159/160, Income-tax Act, 2025 |
| Due date | 31 March 2027, if the ITR is filed under section 139(1) or 139(4) | 12 months after the tax year ends (31 March 2028 for 2026-27), if the return is filed under section 263(1) or 263(4) |
| Accountant verification | Not required | If foreign tax for the year is ₹1,00,000 or more |
The Form 67 deadline comes from CBDT (Central Board of Direct Taxes) Notification No. 100/2022 of 18 August 2022, which amended Rule 128(9) from 1 April 2022. The portal’s Form 67 user manual and FAQ (last modified 24 September 2025) still give the old deadline (the ITR due date), but the amended rule prevails.
Under the 2026 Rules, Form No. 67 is a different form: the alternate minimum tax (AMT) report, formerly Form 29C. Don’t use it for foreign tax credit.
Documents you need for Form 67
- Broker statement showing each dividend’s gross amount and US tax withheld, by date. This is your proof of deduction.
- Certificate or statement of income and tax: from the foreign tax authority, from the person who deducted the tax (in the US, Form 1042-S), or signed by you with proof of deduction. Form 1042-S follows the US calendar year, so January–March 2026 dividends appear only on the 2026 form, due to you by 15 March 2027; a self-signed statement avoids the wait.
- A valid W-8BEN, the US form that claims the treaty rate. It lapses at the end of the third calendar year after the year of signing; without it, withholding is 30%.
- State Bank of India (SBI) telegraphic transfer (TT) buying rates. Convert the US tax at the rate on the last day of the month before the month of deduction (unchanged in Rule 76). Convert the dividend under Rule 115 at the rate on the last day of the month before it is declared, distributed or paid.
If you invest through a GIFT City platform such as Platizio Global (accounts held with ViewTrade’s GIFT City (IFSC) entity), the same tax rules apply; ask which statement shows the gross dividend and US tax withheld.
How to file Form 67 on the income tax portal, step by step
You need an e-filing login and an active PAN (permanent account number).
- Log in at incometax.gov.in.
- Open the form: e-File > Income Tax Forms > File Income Tax Forms, then select Form 67 (or type “Form 67” in the search box).
- Pick the year: AY 2026-27 for FY 2025-26 income, then “Continue” and “Let’s Get Started”.
- Fill Part A: personal details, plus foreign income and the credit claimed, country by country.
- Fill Part B only if it applies: foreign tax refunded after a carry-back of losses, or disputed foreign tax.
- Complete the verification, a self-declaration under Rule 128.
- Attach the certificate or statement, and proof of the tax deducted.
- Preview and e-verify (“Proceed to e-Verify”) with an Aadhaar one-time password (OTP), electronic verification code (EVC) or digital signature certificate (DSC). Save the acknowledgement number.
File early. In reported cases where the Centralised Processing Centre (CPC) processed a return without Form 67, it refused the credit in the section 143(1) intimation, creating a tax demand.
How Form 67 links to Schedules OS, FSI and TR
Report the same figures in ITR-2, or ITR-3 if you have business income.
- Schedule OS (income from other sources): the gross dividend.
- Schedule FSI (foreign source income): for each country, the income, tax paid outside India, Indian tax payable on it, the relief available (the lower of the two) and the treaty article.
- Schedule TR (tax relief): country totals, with relief under section 90 for the US.
Form 67 must match Schedule FSI, or the credit can be refused. Your holdings go in Schedule FA (foreign assets); see what happens if you don’t report foreign stocks and how to report US stocks in your ITR.
How much foreign tax credit you get on US dividends
Under Article 10 of the India–US double taxation avoidance agreement (DTAA), the US can tax your dividends at up to 25% of the gross amount. India taxes the gross dividend at your slab rate and credits the lower of the US tax and the Indian tax on that dividend. US tax withheld above the treaty rate is not creditable.
So you get full credit only at the 25% and 30% slabs, where your rate with 4% cess is at least 25%. Below that, part of the US tax is a permanent cost. The example uses the common marginal-rate method. Some experts apply your average tax rate instead, which usually gives less credit, so ask a chartered accountant (CA) about large amounts.
Worked example: Form 67 for a US$500 dividend
A US company declares and pays a US$500 dividend in January 2026. With a valid W-8BEN, $125 (25%) is withheld and $375 reaches you. Both amounts are converted at SBI’s TT buying rate on 31 December 2025, the last day of the month before payment: ₹89.47.
- Gross dividend: 500 × 89.47 = ₹44,735 (Schedules OS and FSI)
- US tax: 125 × 89.47 = ₹11,183.75, about ₹11,184 (Schedule FSI and Form 67)
The credit is the lower of ₹11,184 and the Indian tax on ₹44,735:
| Slab (with 4% cess) | Indian tax | Credit | Extra tax in India | US tax lost |
|---|---|---|---|---|
| 30% (31.2%) | ₹13,957 | ₹11,184 | ₹2,773 | ₹0 |
| 20% (20.8%) | ₹9,305 | ₹9,305 | ₹0 | ₹1,879 |
| New regime, total income up to ₹12 lakh | ₹0 (rebate) | ₹0 | ₹0 | ₹11,184 |
In the last row, the section 87A rebate (up to ₹60,000) makes your Indian tax nil, so there is no credit and the 25% US tax is your final cost; you still report the dividend. Under the average-rate view, a new-regime taxpayer with ₹30 lakh of income would get ₹7,444 of credit, not ₹11,184.
Common Form 67 mistakes
- Filing Form 67 after the return is processed, or not at all.
- Figures that don’t match Schedule FSI.
- Reporting the net dividend ($375) instead of the gross ($500).
- Converting at the payment-date rate, or not at SBI’s TT buying rate.
- Claiming 30% withholding: the credit stays capped at the 25% treaty amount.
- Claiming tax collected at source (TCS) on your remittance in Form 67; TCS is claimed in the ITR.
What happens if you file Form 67 late
The Madras High Court (Duraiswamy Kumaraswamy, 6 October 2023) and the Income Tax Appellate Tribunal (ITAT) in Chennai (Nanda Kumar Parthasarathy v. ITO, 7 July 2025) held the time limit to be directory and allowed credit on late forms. Both concerned years before the 2022 amendment, so treat them as grounds for appeal, not a safe harbour.
Sources
- Income Tax Department: Form 67 user manual — https://www.incometax.gov.in/iec/foportal/help/statutory-forms/popular-form/form67-um
- Income Tax Department: Form 67 FAQs — https://www.incometax.gov.in/iec/foportal/help/statutory-forms/popular-form/form67-faq
- CBDT: FAQs on Form No. 44 and Form No. 45 — https://www.incometaxindia.gov.in/documents/d/guest/form-44-45-faqs
- Income Tax Department: Rule 76, Income-tax Rules, 2026 — https://www.incometaxindia.gov.in/w/rule-76-3
- Income Tax Department: Form No. 67 under the Income-tax Rules, 2026 (AMT report) — https://www.incometaxindia.gov.in/documents/d/guest/fn-67
- Income Tax Department: ITR-2 for AY 2026-27 — https://www.incometaxindia.gov.in/documents/d/guest/itr-2-2026-eng-pdf
- India–US income tax treaty (IRS) — https://www.irs.gov/pub/irs-trty/india.pdf
- IRS: Instructions for Form 1042-S — https://www.irs.gov/instructions/i1042s
- IRS: Instructions for Form W-8BEN — https://www.irs.gov/instructions/iw8ben
- ITAT Chennai: Nanda Kumar Parthasarathy v. ITO, ITA 853/Chny/2025, 7 July 2025 — https://itat.gov.in/public/files/upload/1752061951-UAnPup-1-TO.pdf
- EY: Madras High Court grants foreign tax credit on delayed filing of Form 67 (15 March 2024) — https://www.ey.com/en_in/technical/alerts-hub/2024/03/madras-high-court-grants-foreign-tax-credit-on-delayed-filing-of-form-67
- itatonline: Guide to Rule 128 (foreign tax credit) — https://itatonline.org/articles_new/?p=2895
This article is general information, not tax, legal or investment advice, and not a personalised recommendation. Tax rules, forms and deadlines are stated as of 15 October 2026 and can change; consult a chartered accountant about your own situation. Investments in US stocks and ETFs are subject to market risk, currency risk and tax implications, and returns are not guaranteed. Platizio Global is operated by Platizio Services LLP, a mutual fund distributor registered with the Association of Mutual Funds in India (AMFI), and offers US stocks and ETFs through ViewTrade International IFSC Private Limited, ViewTrade’s GIFT City entity regulated by the International Financial Services Centres Authority (IFSCA), with which accounts are opened and held. Platizio is a referral partner and may receive remuneration from ViewTrade.