Last updated: 15 October 2026 · By Analyst, Platizio Global
If you are resident and ordinarily resident in India, you must list every US share and exchange-traded fund (ETF) in Schedule FA of your return, at any value. The Schedule FA penalty under the Black Money Act is ₹10 lakh; since 1 October 2024, it doesn’t apply if your foreign assets other than immovable property total ₹20 lakh or less.
Key takeaways
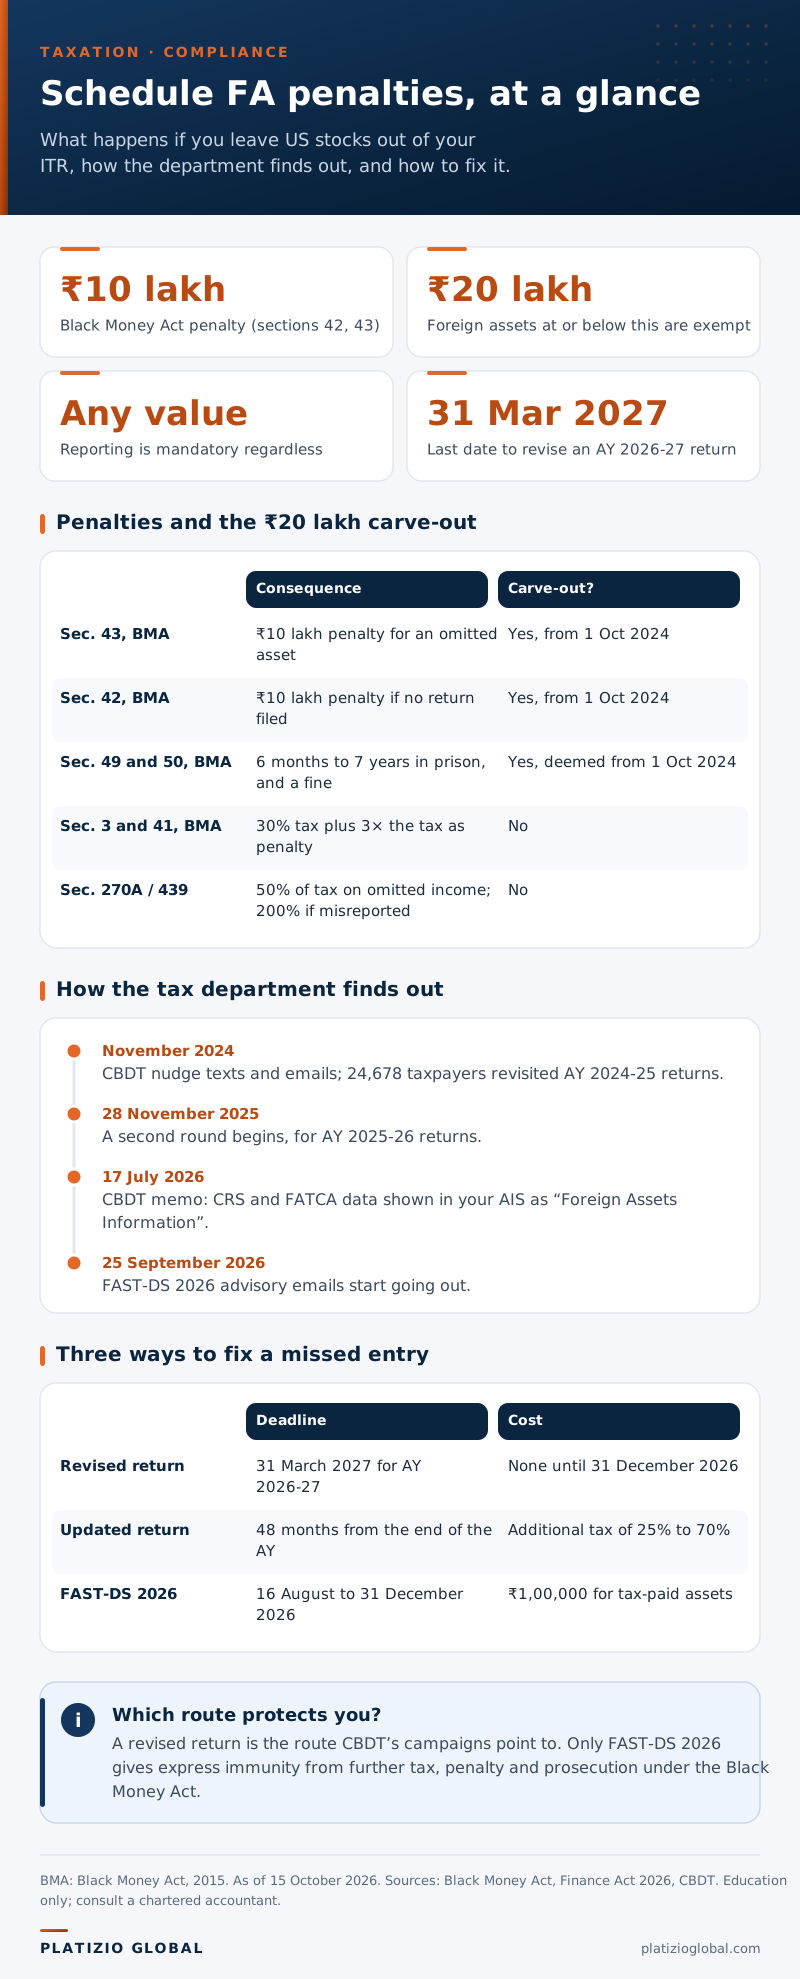
- Schedule FA penalty: ₹10 lakh under sections 42 and 43 of the Black Money Act, unless your foreign assets other than immovable property total ₹20 lakh or less.
- Prosecution: Finance Act 2026 gave sections 49 and 50 the same ₹20 lakh carve-out, deemed effective from 1 October 2024.
- Reporting stays mandatory at any value, even if your income is below the taxable limit.
- Fix window: you can revise your assessment year (AY) 2026-27 return until 31 March 2027; the FAST-DS 2026 scheme closes on 31 December 2026.
Schedule FA penalty under the Black Money Act
| Provision | When it applies | Consequence | ₹20 lakh carve-out |
|---|---|---|---|
| Section 43, Black Money Act | Foreign asset or income left out of a filed return, or misreported | ₹10 lakh penalty | Yes, from 1 October 2024 |
| Section 42, Black Money Act | No return filed when one was required | ₹10 lakh penalty | Yes, from 1 October 2024 |
| Sections 49 and 50, Black Money Act | Prosecution for wilful failures | Rigorous imprisonment of 6 months to 7 years, and a fine | Yes, deemed from 1 October 2024 (Finance Act 2026) |
| Sections 3 and 41, Black Money Act | “Undisclosed asset” whose source you can’t explain | 30% tax plus a penalty of three times the tax | No |
| Section 270A, Income-tax Act, 1961 (section 439 of the 2025 Act) | Foreign income, such as dividends, left out | 50% of the tax on under-reported income; 200% if misreported | No |
Sections 42, 43, 49 and 50 “shall not apply” where the aggregate value of your foreign assets (other than immovable property) “does not exceed twenty lakh rupees”. Before 1 October 2024, the penalty spared only foreign bank accounts with balances totalling up to ₹5 lakh.
- It is an aggregate test. Shares, ETFs, foreign bank balances and employee stock awards count together. ₹20 lakh was about US$22,354 at ₹89.47 to the dollar on 31 December 2025.
- The valuation date is not settled, so don’t count on the relief if you are anywhere near ₹20 lakh.
Schedule FA in your ITR: who must report and how to fill it
Schedule FA (foreign assets) applies if you are resident and ordinarily resident (ROR); non-resident Indians (NRIs) and residents who are not ordinarily resident (RNOR) are exempt. An ROR with any foreign asset must file an income tax return (ITR) even with income below the basic exemption limit. This applies to AY 2026-27 under the 1961 Act and, from tax year 2026-27, under section 263 of the Income-tax Act, 2025.
Schedule FA follows the calendar year. For AY 2026-27, report everything you held at any time from 1 January to 31 December 2025, including shares you sold, with their gross sale proceeds. Shares bought in January–March 2026 go in next year’s schedule. Two tables matter:
- Table A2 (foreign custodial accounts): your brokerage account, its peak and closing balance, and gross amounts credited, such as dividends and sale proceeds.
- Table A3 (foreign equity and debt interest): one row per holding, with the date acquired, initial, peak and closing values, gross amounts credited and gross sale proceeds.
Convert at State Bank of India’s (SBI’s) telegraphic transfer (TT) buying rate: initial value at the acquisition-date rate, peak at the peak-date rate, and closing value and income at the 31 December rate. For the other schedules, see how to report US stocks in your ITR.
If you hold US shares through a GIFT City platform such as Platizio Global (accounts held with ViewTrade’s GIFT City (IFSC) entity), they still need reporting, because the tables cover beneficial interests, and they are taxed the same way. There is no official guidance yet on how to show the GIFT City account itself, so agree the entries with a chartered accountant (CA).
How the tax department finds out
India receives foreign-account data each year under the Common Reporting Standard (CRS) and the US Foreign Account Tax Compliance Act (FATCA). The Central Board of Direct Taxes (CBDT) uses it in three ways:
- Nudge campaigns. After CBDT’s November 2024 texts and emails, 24,678 taxpayers revisited their AY 2024-25 returns, disclosing ₹29,208 crore of foreign assets and ₹1,089.88 crore of foreign-source income, CBDT says. A second round, for AY 2025-26 returns, began on 28 November 2025.
- The AIS report. Under a CBDT office memorandum of 17 July 2026, this data appears in your Annual Information Statement (AIS) under Compliance Portal > Reports > “Foreign Assets Information”: 2022–2024 now, and 2025 once received (expected in September or October 2026). CBDT says it is not a complete record and is meant “to facilitate, and not to investigate”.
- FAST-DS emails. Since 25 September 2026, advisory emails about the Foreign Assets of Small Taxpayers Disclosure Scheme (FAST-DS) 2026 have gone out. Their links route through a third-party tracking domain, so type the portal address yourself.
How to fix a missed Schedule FA entry
| Route | Deadline | Cost | What it does |
|---|---|---|---|
| Revised return | 31 March 2027 for AY 2026-27 | None until 31 December 2026; expected after that: ₹1,000 (total income up to ₹5 lakh) or ₹5,000 | Corrects the return, which section 43 covers; no express immunity |
| Updated return (ITR-U) | 48 months from the end of the AY | Additional tax of 25% to 70% of tax and interest, depending on timing | Barred once treaty or CRS/FATCA data about you has been communicated to you; no Black Money Act protection, practitioners say |
| FAST-DS 2026 | 16 August to 31 December 2026 | ₹1,00,000 for tax-paid assets, or assets acquired while non-resident, up to ₹5 crore; 30% tax plus 100% of that tax for undisclosed assets up to ₹1 crore | Immunity from further tax, penalty and prosecution under the Black Money Act |
A revised return is the route CBDT’s campaigns point to; only FAST-DS gives express immunity. If you have not filed for AY 2026-27 at all, the belated-return deadline is 31 December 2026.
Worked example: US$8,000 of US stocks bought in 2025
Priya, a salaried ROR with no other foreign assets, buys US shares and ETFs for $8,000 on 12 March 2025 through a US-custodied account and sells nothing in 2025. Her holding peaks at $9,400 on 10 December and ends the year at $9,150. She receives three gross dividends of $20 ($5 withheld from each) in May, August and November.
Her Table A3 entries for AY 2026-27:
| Column | Amount | Rate used | ₹ value |
|---|---|---|---|
| Initial value | $8,000 | ₹86.85 (12 March 2025) | ₹6,94,800 |
| Peak value | $9,400 | ₹89.45 (10 December 2025) | ₹8,40,830 |
| Closing value | $9,150 | ₹89.47 (31 December 2025) | ₹8,18,651 |
| Gross amount credited | $60 (dividends) | ₹89.47 (31 December 2025) | ₹5,368 |
Her dividends also go in Schedules OS (other sources) and FSI (foreign source income), converted at the month-end rate before each payment: 20 × (84.25 + 87.15 + 88.20) = ₹5,192, with US tax of ₹1,298 claimed through Form 67.
Her foreign assets peak at about ₹8.4 lakh, so the ₹10 lakh penalty and prosecution don’t apply under the current provisos. Leaving out the dividends could still cost a penalty of 50% of the tax on them, plus interest, and her account data can appear in AIS. If she filed without Schedule FA, she can revise by 31 March 2027.
What tribunals have said about Schedule FA non-disclosure
Penalties are not automatic. Chennai benches of the Income Tax Appellate Tribunal (ITAT) deleted section 43 penalties in Kumar Ramanathan ([2026] 186 taxmann.com 784), where the money was tax-paid and traceable, and in Krishore Kumar Rajagopal (2026), over unintentional non-disclosure of employee stock options. But in Shobha Harish Thawani ([2023] 154 taxmann.com 564), the Mumbai ITAT upheld the penalty although the interest income was declared, because the asset was missing from Schedule FA.
Sources
- Black Money Act (India Code text) — https://www.indiacode.nic.in/bitstream/123456789/2147/1/A201522.pdf
- Income Tax Department: ITR-2 for AY 2026-27 (Schedule FA) — https://www.incometaxindia.gov.in/documents/d/guest/itr-2-2026-eng-pdf
- CBDT: Press release on the second NUDGE initiative for foreign assets (27 November 2025) — https://incometaxindia.gov.in/Lists/Press%20Releases/Attachments/1234/PressRelease-CBDT-launches-2nd-NUDGE-initiative-to-strengthen-voluntary-compliance-in-respect-of-Foreign-Assets.pdf
- CBDT: Office memorandum on CRS data in AIS (17 July 2026) — https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-07/OM_17.07.2026_Hosting%20of%20Note%20on%20CRS%20in%20AIS.pdf
- CBDT: Tutorial on updated return — https://incometaxindia.gov.in/Tutorials/51.Updated-Return.pdf
- Income Tax Department: Section 234-I, Income-tax Act, 1961 (fee for revised return) — https://www.incometaxindia.gov.in/w/section-234i
- Lakshmikumaran & Sridharan: Non-disclosure of foreign assets in the ITR and the penalty threshold — https://www.lkslaw.com/insights/articles/non-disclosure-of-foreign-assets-in-the-itr-ownership-valuation-threshold-for-penalty-under-the-black-money-act
- Taxmann: FAQs on reporting in ITR schedules — https://www.taxmann.com/post/blog/faqs-income-tax-returns-itr-reporting-in-schedules-in-itr/
- Patron Accounting: Revised return deadline extended to 12 months — https://www.patronaccounting.com/blog/revised-return-deadline-extended-12-months-itr-2026
- Vialto Partners: FAST-DS 2026 rules, forms and FAQs notified — https://vialtopartners.com/regional-alerts/india-global-mobility-tax-foreign-assets-of-small-taxpayers-disclosure-scheme-rules-2026-rules-forms-and-faqs-notified
- CBDT: Notification No. 114/2026, Foreign Assets of Small Taxpayers – Disclosure Scheme Rules, 2026 (14 August 2026) — https://www.incometaxindia.gov.in/documents/d/guest/notification-no-114-2026-pdf
- Taxmann: ITAT deletes Black Money Act penalty on disclosed foreign funds (Kumar Ramanathan) — https://www.taxmann.com/post/blog/itat-deletes-black-money-act-penalty-on-disclosed-foreign-funds/
This article is general information, not tax, legal or investment advice, and not a personalised recommendation. Tax rules, penalties and deadlines are stated as of 15 October 2026 and can change; consult a chartered accountant about your own situation. Investments in US stocks and ETFs are subject to market risk, currency risk and tax implications, and returns are not guaranteed. Platizio Global is operated by Platizio Services LLP, a mutual fund distributor registered with the Association of Mutual Funds in India (AMFI), and offers US stocks and ETFs through ViewTrade International IFSC Private Limited, ViewTrade’s GIFT City entity regulated by the International Financial Services Centres Authority (IFSCA), with which accounts are opened and held. Platizio is a referral partner and may receive remuneration from ViewTrade.