Last updated: 19 October 2026 · By Analyst, Platizio Global
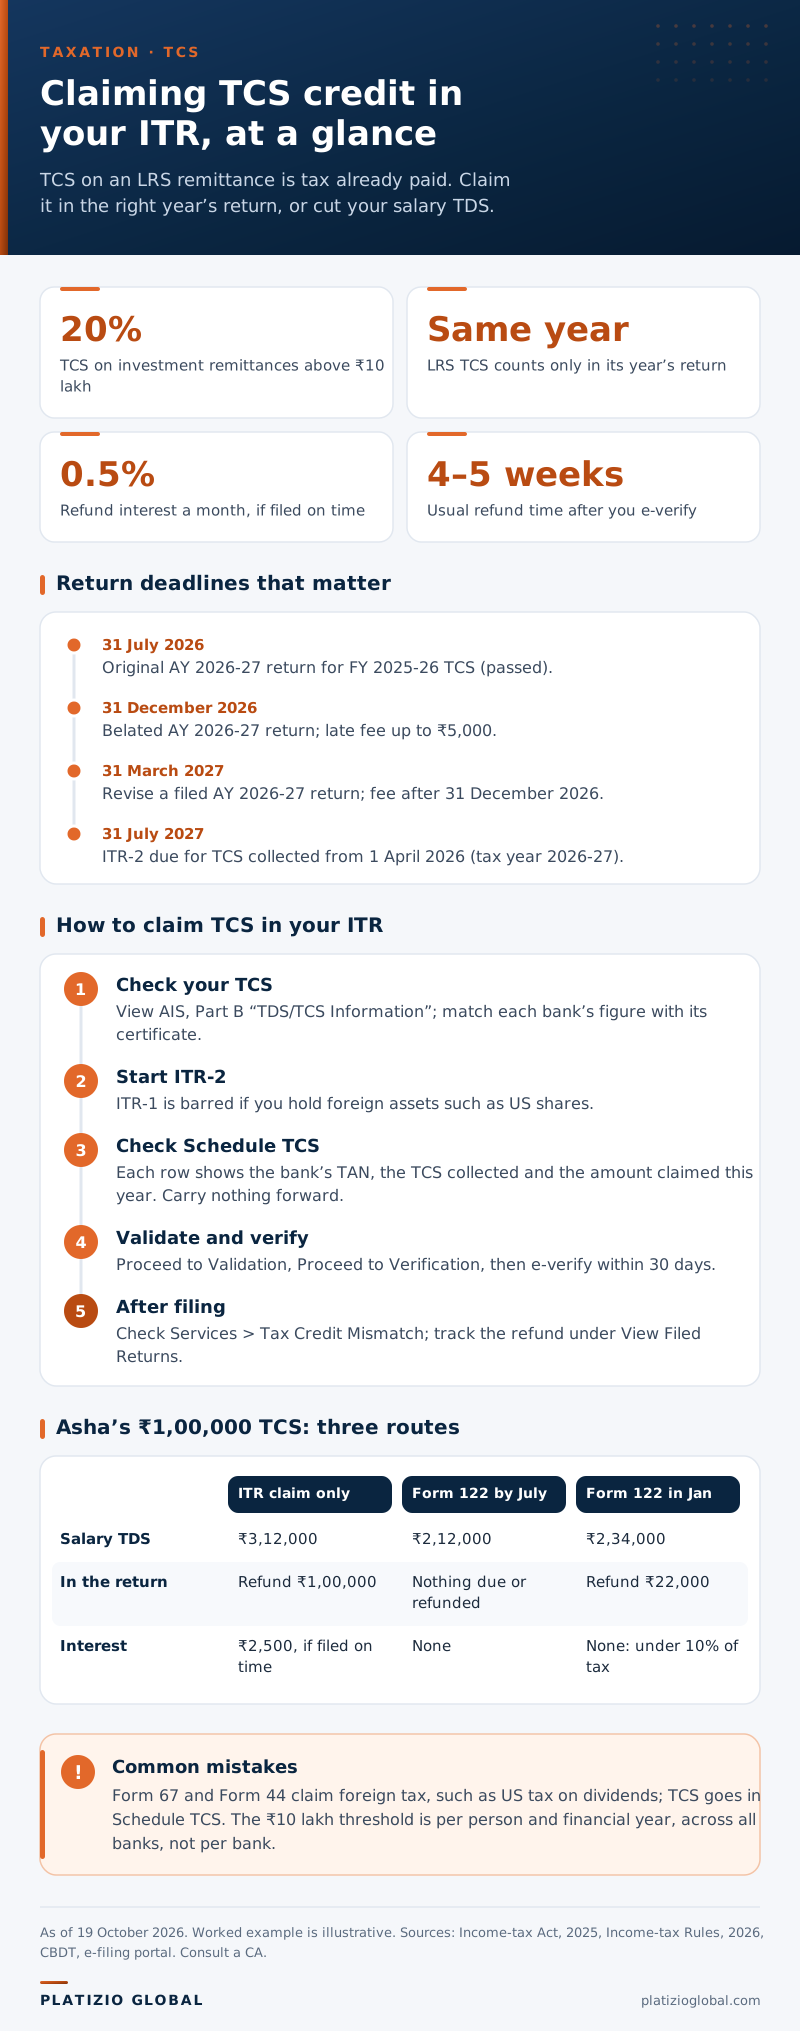
Tax collected at source (TCS) on money sent abroad under the Liberalised Remittance Scheme (LRS) is tax already paid in your name. Claim it in Schedule TCS of your income tax return (ITR) for the year it was collected: financial year (FY) 2025-26 TCS in the assessment year (AY) 2026-27 return; TCS from 1 April 2026 in the tax year 2026-27 return (ITR-2 due 31 July 2027). Any excess is refunded. Salaried people can instead have their employer deduct less tax.
Key takeaways
- Same year only: LRS TCS counts only in the return for its year of collection.
- Use ITR-2: ITR-1 is barred if you hold foreign assets such as US shares.
- FY 2025-26 TCS unclaimed? File a belated return by 31 December 2026 or revise a filed one by 31 March 2027 (fee after 31 December).
- Interest: 0.5% a month from 1 April after the year if you file on time; none on refunds under 10% of tax.
How TCS credit works: old and new law
Once your LRS remittances in a financial year exceed ₹10 lakh across all banks, your bank collects 20% on investment remittances, including to GIFT City accounts, and credits it to your PAN (permanent account number) as tax paid (TCS rates on LRS). Section 206C(1G) of the 1961 Act (FY 2025-26) taxed the amount “in excess of ten lakh rupees”; section 394(1) of the 2025 Act does not say whether only the excess is taxed, but banks such as HDFC collect only on the excess. Forms changed on 1 April 2026, when the Income-tax Act, 2025 replaced the 1961 Act:
| FY 2025-26 (1961 Act) | From 1 April 2026 (2025 Act) | |
|---|---|---|
| Credit rule and return | Rule 37-I: AY 2026-27 return | Rule 203: tax year 2026-27 return |
| Bank’s certificate | Form 27D | Form 133 |
| Statement to check | Form 26AS | Form 168 (earlier 26AS) |
Which ITR to file, and the deadlines
Any foreign asset or foreign income rules out ITR-1, so holders of US shares, including through GIFT City, file ITR-2 (ITR-3 with business income) and list the shares in Schedule FA (foreign assets); see tax on US stocks through GIFT City.
| FY 2025-26 TCS (AY 2026-27) | Tax year 2026-27 TCS | |
|---|---|---|
| Original return (ITR-2) | 31 July 2026 (passed) | 31 July 2027 |
| Belated return | 31 December 2026; late fee up to ₹5,000 | 31 December 2027 |
| Revised return | 31 March 2027; fee after 31 December 2026: ₹1,000 (income up to ₹5 lakh) or ₹5,000 | 31 March 2028; fee after 31 December 2027 |
An updated return (ITR-U) cannot create or increase a refund (section 139(8A)).
How to claim TCS in your ITR, step by step
- Check your TCS: e-File > Income Tax Returns > View AIS (annual information statement), Part B “TDS/TCS Information”; match each bank’s figure with its certificate.
- Start the return (ITR-2 user manual): e-File > Income Tax Returns > File Income Tax Return; pick the year, “Online”, your status and ITR-2, then “Let’s Get Started”.
- Check Schedule TCS (Tax Paid section): each row shows the bank’s TAN (tax deduction and collection account number), the TCS collected and the amount claimed this year, which cannot exceed it. Carry nothing forward.
- Validate and verify: Proceed to Validation, Proceed to Verification, then e-verify within 30 days.
- After filing: check Services > Tax Credit Mismatch; track the refund at e-File > Income Tax Returns > View Filed Returns.
Adjust TCS against salary TDS through your employer
Section 392(4) of the 2025 Act makes your employer count TCS you declare for the same tax year and cut the tax deducted at source (TDS) from your salary. Use Part C of Form 122 (formerly Forms 12B and 12BAA); it is optional, with no prescribed time limit. The employer can only reduce later deductions, not repay TDS already deducted, so declare early.
Worked example: ₹15 lakh to a GIFT City account
Asha’s taxable salary for tax year 2026-27 is ₹24,00,000 (default regime): tax of ₹3,00,000 plus 4% cess is ₹3,12,000, or ₹26,000 a month of TDS. On 10 July 2026 she sends ₹15,00,000 to her GIFT City account, her first LRS remittance that year. As banks charge it, TCS is 20% × (₹15,00,000 − ₹10,00,000) = ₹1,00,000.
| A. ITR claim only | B. Form 122 before July payroll | C. Form 122 in January 2027 | |
|---|---|---|---|
| Salary TDS | ₹3,12,000 | ₹78,000 (April–June) + ₹1,34,000 over July–March (₹3,12,000 − ₹78,000 − ₹1,00,000) = ₹2,12,000 | ₹2,34,000 (April–December), then nil: ₹3,12,000 − ₹2,34,000 − ₹1,00,000 is −₹22,000 |
| In the return | Refund ₹1,00,000 | Nothing due or refunded | Refund ₹22,000 |
| Interest (section 437) | ₹2,500 (April–August 2027: 5 months × 0.5%, if filed on time) | None | None: under 10% of ₹3,12,000 |
TCS refund timing and interest
Processing starts only after you e-verify; the portal says refunds usually take 4–5 weeks. They need a pre-validated bank account and fail if your PAN is inoperative (not linked with Aadhaar). Interest is 0.5% for every month or part of a month (section 437; section 244A for AY 2026-27):
- Filed by the due date: from 1 April after the year until the refund.
- Belated return: from the filing date.
- No interest on refunds under 10% of your tax, or for delays you cause.
TCS paid from a family member’s account
Credit goes to the account holder: TCS on tuition paid from a parent’s account is the parent’s, not the child’s.
- FY 2025-26 TCS: Rule 37-I(1A) let the remitter declare to the bank that the income was assessable in another person’s hands (say, a minor’s, clubbed with a parent’s), so the bank reported the TCS in that name.
- From 1 April 2026 (unsettled): Rule 203(2) keeps that declaration, but Rule 203(7) credits LRS TCS to the account holder “irrespective of” sub-rules (1) to (6). With no CBDT clarification by 19 October 2026, assume it stays there.
TCS not showing in Form 26AS or Form 168
Your credit is capped at what Form 26AS (Form 168 from tax year 2026-27) shows.
- Timing: Form 133 certificates are due 15 August, 15 November, 15 February and 15 June, so January–March TCS may show only around June.
- Wrong or missing entry: ask the bank to file a corrected statement (Form 27EQ; Form 143 from 1 April 2026) with your correct PAN, or flag it through AIS feedback.
- After filing: fix your own error with a revised return; if the section 143(1) intimation disallows TCS, seek rectification once the bank’s correction shows (Services > Rectification > “Tax Credit Mismatch Correction”).
Common mistakes
- Using Form 67 or Form 44: these claim foreign tax, such as US tax on dividends (how Form 67 works); TCS goes in Schedule TCS.
- Counting ₹10 lakh per bank: the threshold is per person and financial year, across all banks.
Sources
- Income Tax Department: Section 394, Income-tax Act, 2025 (TCS, including LRS remittances) — https://www.incometaxindia.gov.in/w/section-394-6
- Income Tax Department: Section 206C, Income-tax Act, 1961 (sub-section (1G): TCS on LRS remittances to 31 March 2026) — https://www.incometaxindia.gov.in/w/section-206c-39
- Income Tax Department: Rule 203, Income-tax Rules, 2026 (credit for tax collected at source) — https://www.incometaxindia.gov.in/w/rule-203-1
- Income Tax Department: Section 437, Income-tax Act, 2025 (interest on refunds) — https://www.incometaxindia.gov.in/w/section-437-6
- CBDT: FAQs on Form No. 122 (employee’s declaration to employer) — https://www.incometaxindia.gov.in/documents/d/guest/form-122-faqs
- CBDT: FAQs on Form No. 133 (TCS certificate) — https://www.incometaxindia.gov.in/documents/d/guest/form-133-faqs
- CBDT: FAQs on Form No. 168 (earlier Form 26AS) — https://www.incometaxindia.gov.in/documents/d/guest/form-168-faqs
- Income Tax Department, e-filing portal: ITR-1 (Sahaj) FAQs, AY 2026-27 — https://www.incometax.gov.in/iec/foportal/help/all-topics/e-filing-services/file-itr-1-sahaj-online
- Income Tax Department, e-filing portal: Tax credit mismatch FAQs — https://www.incometax.gov.in/iec/foportal/help/e-filing-manage-tax-credit-mismatch-faq
- Income Tax Department, e-filing portal: Refund status user manual — https://www.incometax.gov.in/iec/foportal/help/refund_status_user_manual
- Ministry of Finance: Memorandum explaining the provisions in the Finance Bill, 2026 — https://www.indiabudget.gov.in/doc/memo.pdf
- HDFC Bank: Revision in TCS on LRS transactions w.e.f. 1 April 2026 (accessed 19 October 2026) — https://www.hdfc.bank.in/important-messages/revision-in-tcs-on-lrs-transactions
Platizio Global is operated by Platizio Services LLP, an AMFI-registered mutual fund distributor. Accounts are opened and held with ViewTrade International IFSC Private Limited, which is regulated by the International Financial Services Centres Authority in GIFT City. Platizio is a referral partner, not a broker, investment adviser or research analyst, and may receive remuneration from ViewTrade. This article is for education only. It is not investment, tax or legal advice, or a recommendation to buy, sell or hold any security. The people and figures in the worked examples are for illustration only. Investments in US stocks and ETFs are subject to market risk, currency risk and tax implications; past performance is not indicative of future results, and returns are not guaranteed. Tax rates, forms, deadlines and rules are as of 19 October 2026 and can change; check them with a chartered accountant before you act.